Fortify Alliances Public Adjusters

Public adjusters / No recovery, no fee

Get paid what your claim is really worth

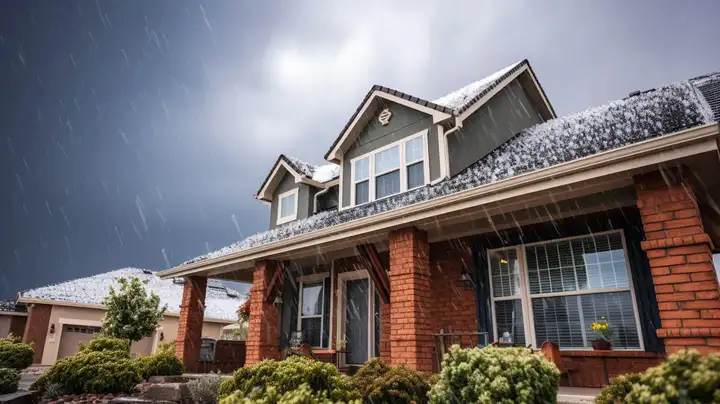
We take your storm, hail, fire, or water damage claim from inspection to final check, so you never negotiate with your insurer alone.

Claims We Handle

Every Kind of Property Damage, One Team in Your Corner.

Whether it’s a single roof or a full commercial building, we document the damage, build the claim, and negotiate the settlement for you.

Why a Public Adjuster

Your Insurer Has an Adjuster. Shouldn’t You?

The adjuster your insurer sends works for them. A licensed public adjuster works only for you, so nothing gets left on the table.


1 of 4: On Your Side, Not the Insurer’s.

01/04

On Your Side, Not the Insurer’s.

Their adjuster protects their bottom line. We protect yours.
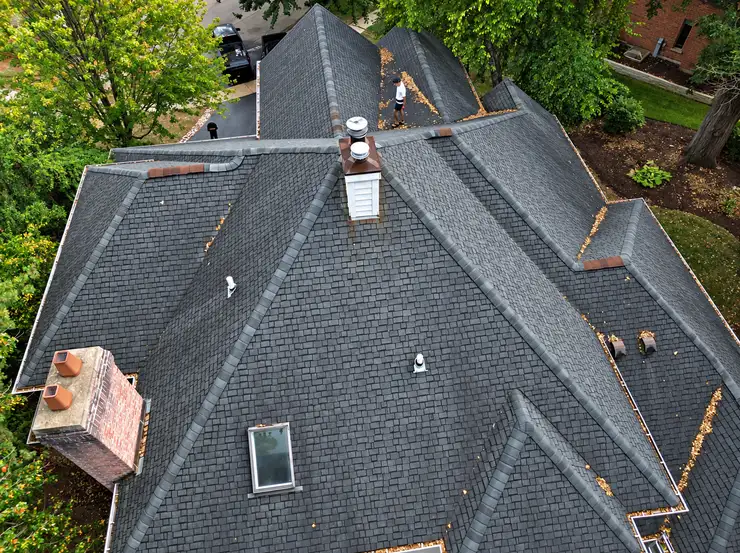
Aerial view of a steep shingled roof with an inspector working on it

1team

In your corner from inspection to final check
Their adjuster’s job is to close your claim fast and keep the payout low. We read your policy line by line, document every bit of damage, and push back on lowball offers.

What you get

  • Policy review & claim strategy
  • Full damage documentation
  • Negotiation with your insurer
  • Paperwork, deadlines & follow-up

02/04

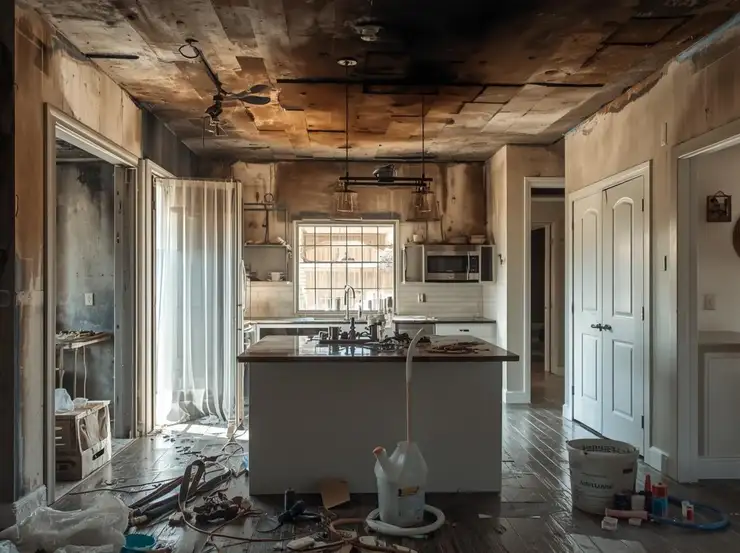
Every Inch Documented.

Damage that’s easy to miss is easy to undervalue.

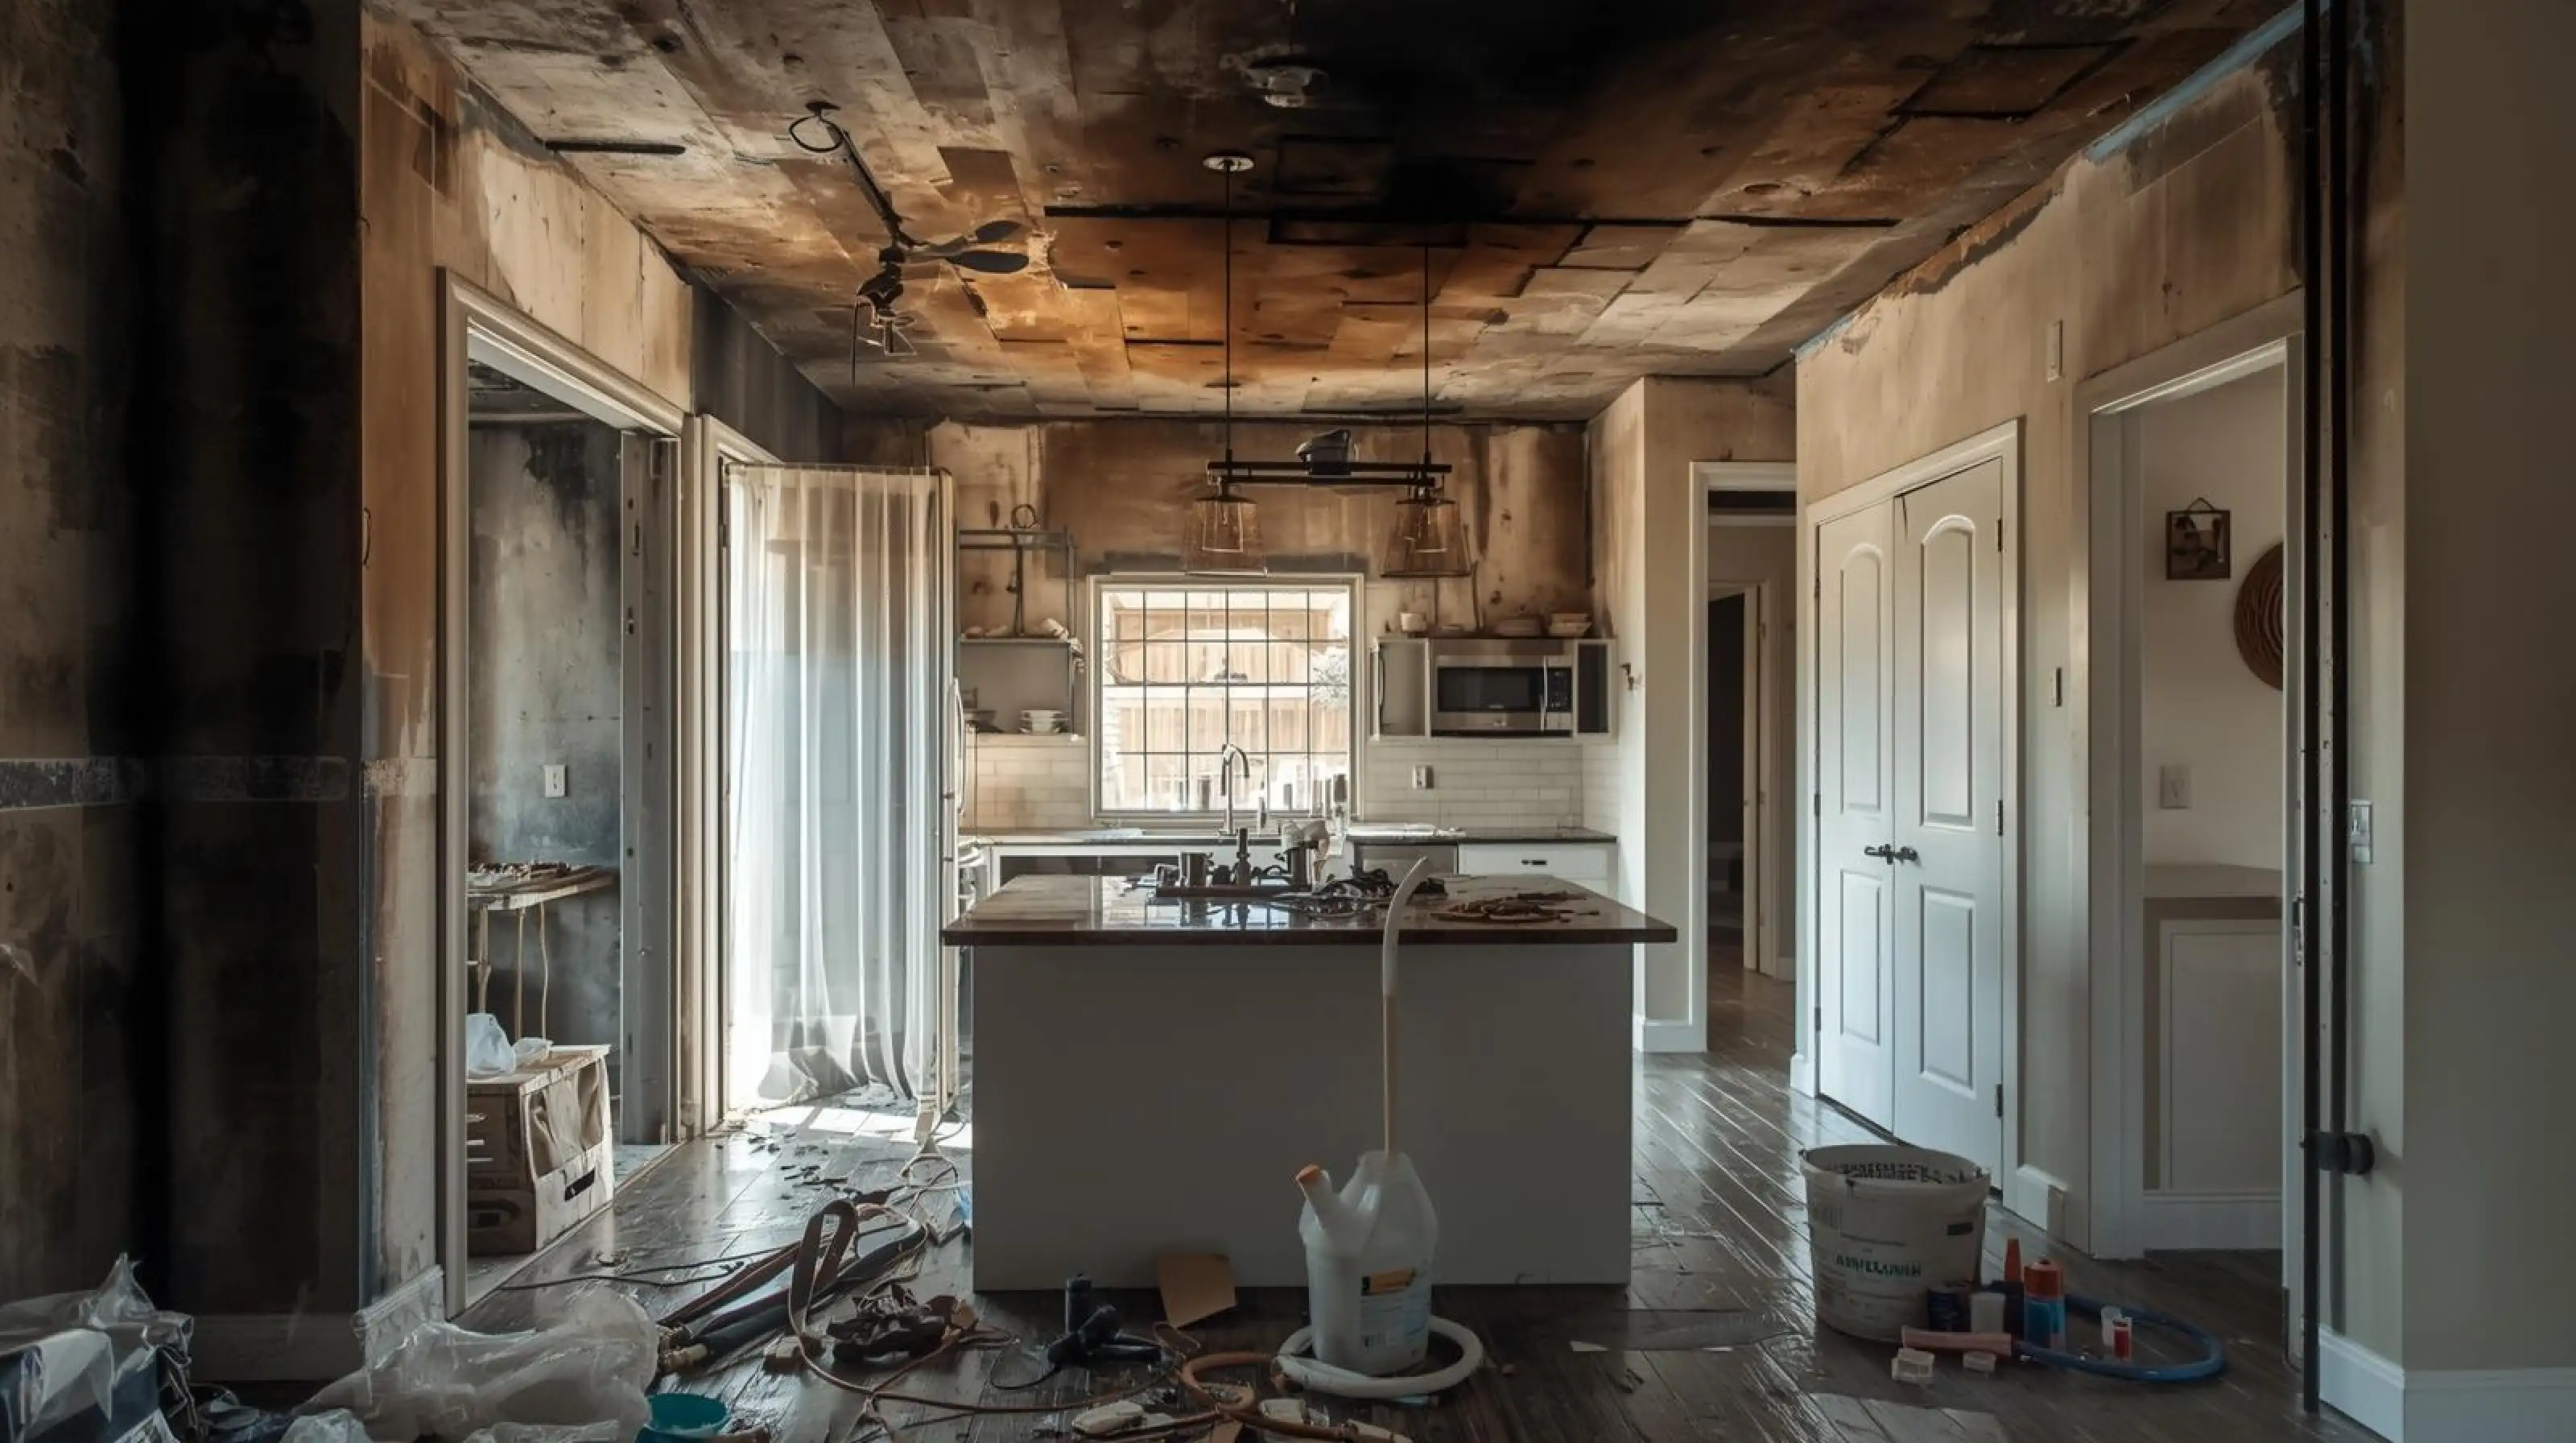
A storm-damaged kitchen with a collapsed ceiling and debris on the floor

4services

Policy review, documentation, negotiation, and follow-up

We inspect every part of the property, photograph and measure the damage, and build a detailed line-by-line estimate, so nothing gets left off your settlement.

What you get

  • Policy review & claim strategy
  • Full damage documentation
  • Negotiation with your insurer
  • Paperwork, deadlines & follow-up

03/04

You Never Negotiate Alone.

We handle every form, deadline, and call with your insurer.
A lit two-story home at dusk surrounded by landscaping

5steps

From property damage to a fair settlement

We prepare and submit your claim with the evidence to back it up, then push back with documentation until the offer reflects the full loss.

What you get

  • Policy review & claim strategy
  • Full damage documentation
  • Negotiation with your insurer
  • Paperwork, deadlines & follow-up

04/04

No Upfront Cost.

We work on contingency, so we only get paid when you do.
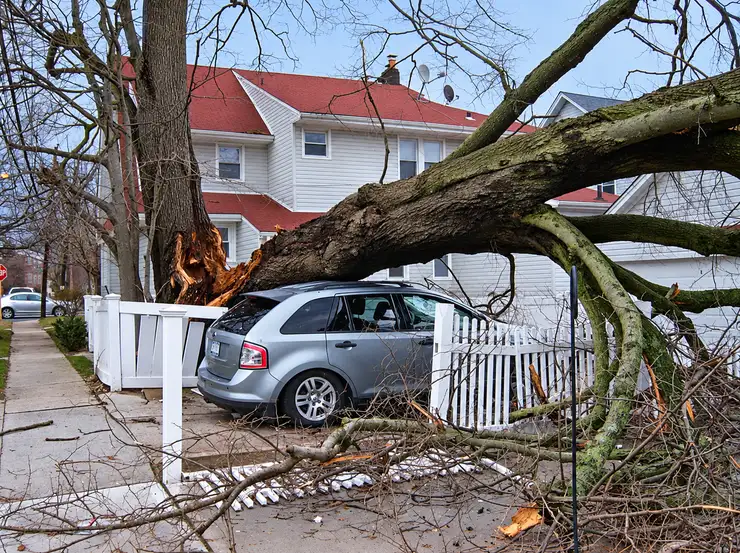
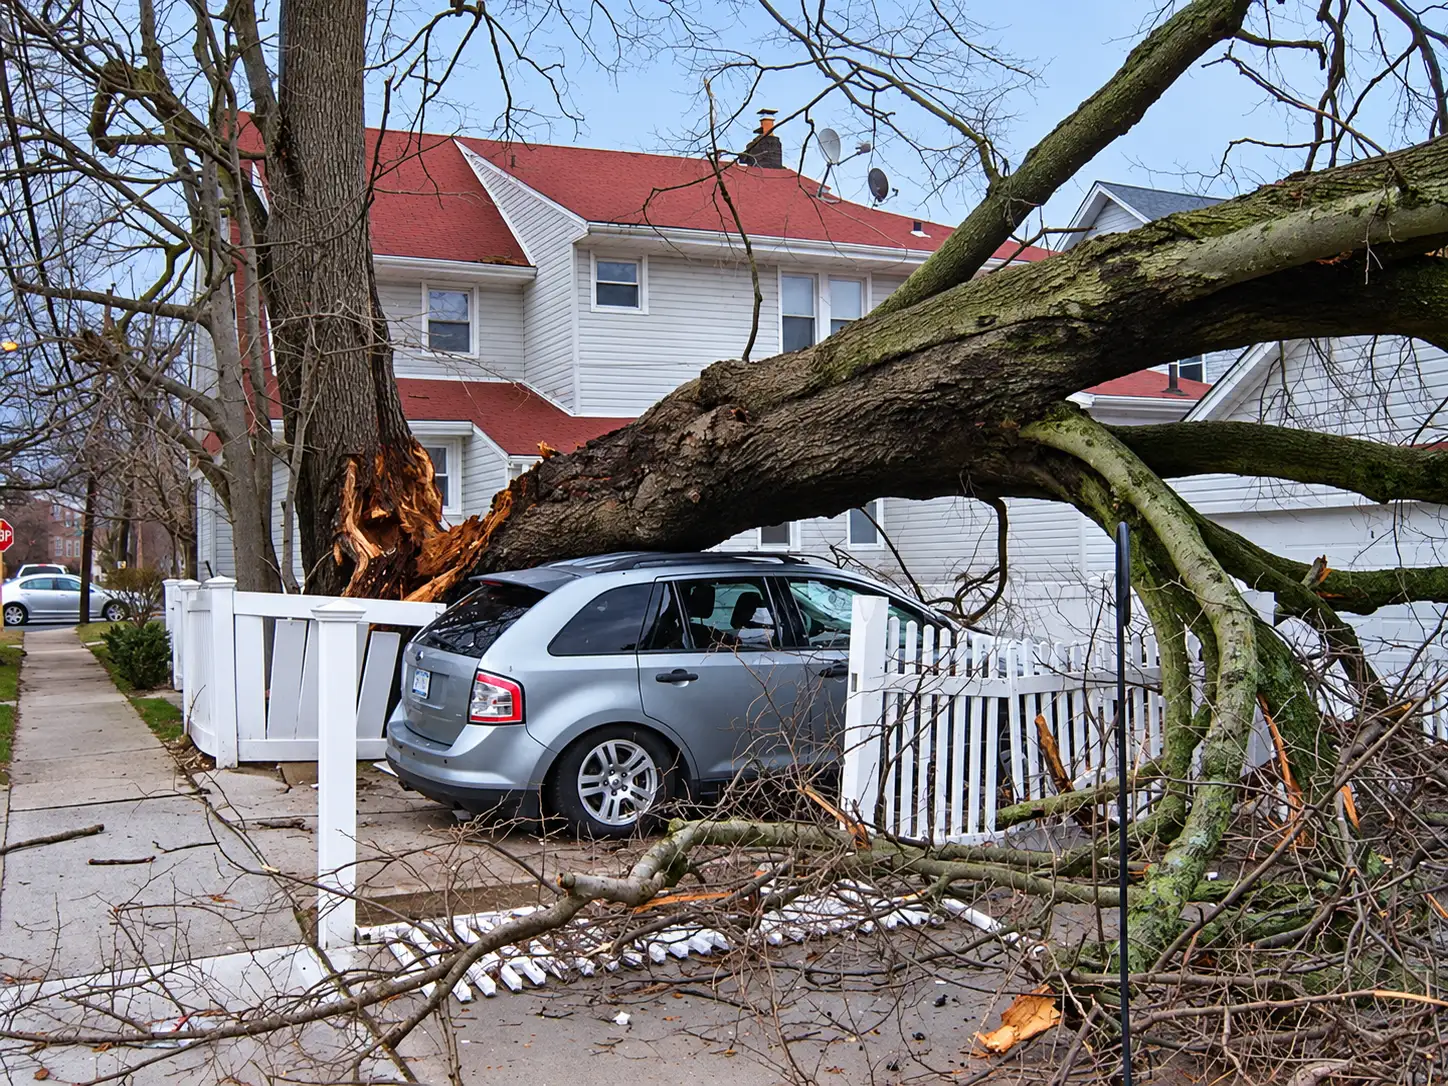
A fallen tree resting on a crushed car in front of a storm-damaged house

$0upfront

We only get paid when you do
We review your policy and the damage at no cost. Once a fair settlement is reached, our fee comes out of the settlement, never out of your pocket.

What you get

  • Policy review & claim strategy
  • Full damage documentation
  • Negotiation with your insurer
  • Paperwork, deadlines & follow-up

Our Process

Five Steps From Damage to a Fair Settlement.

We handle your claim from the first inspection to the final check, so you can focus on getting your home or business back to normal.

Book a free claim
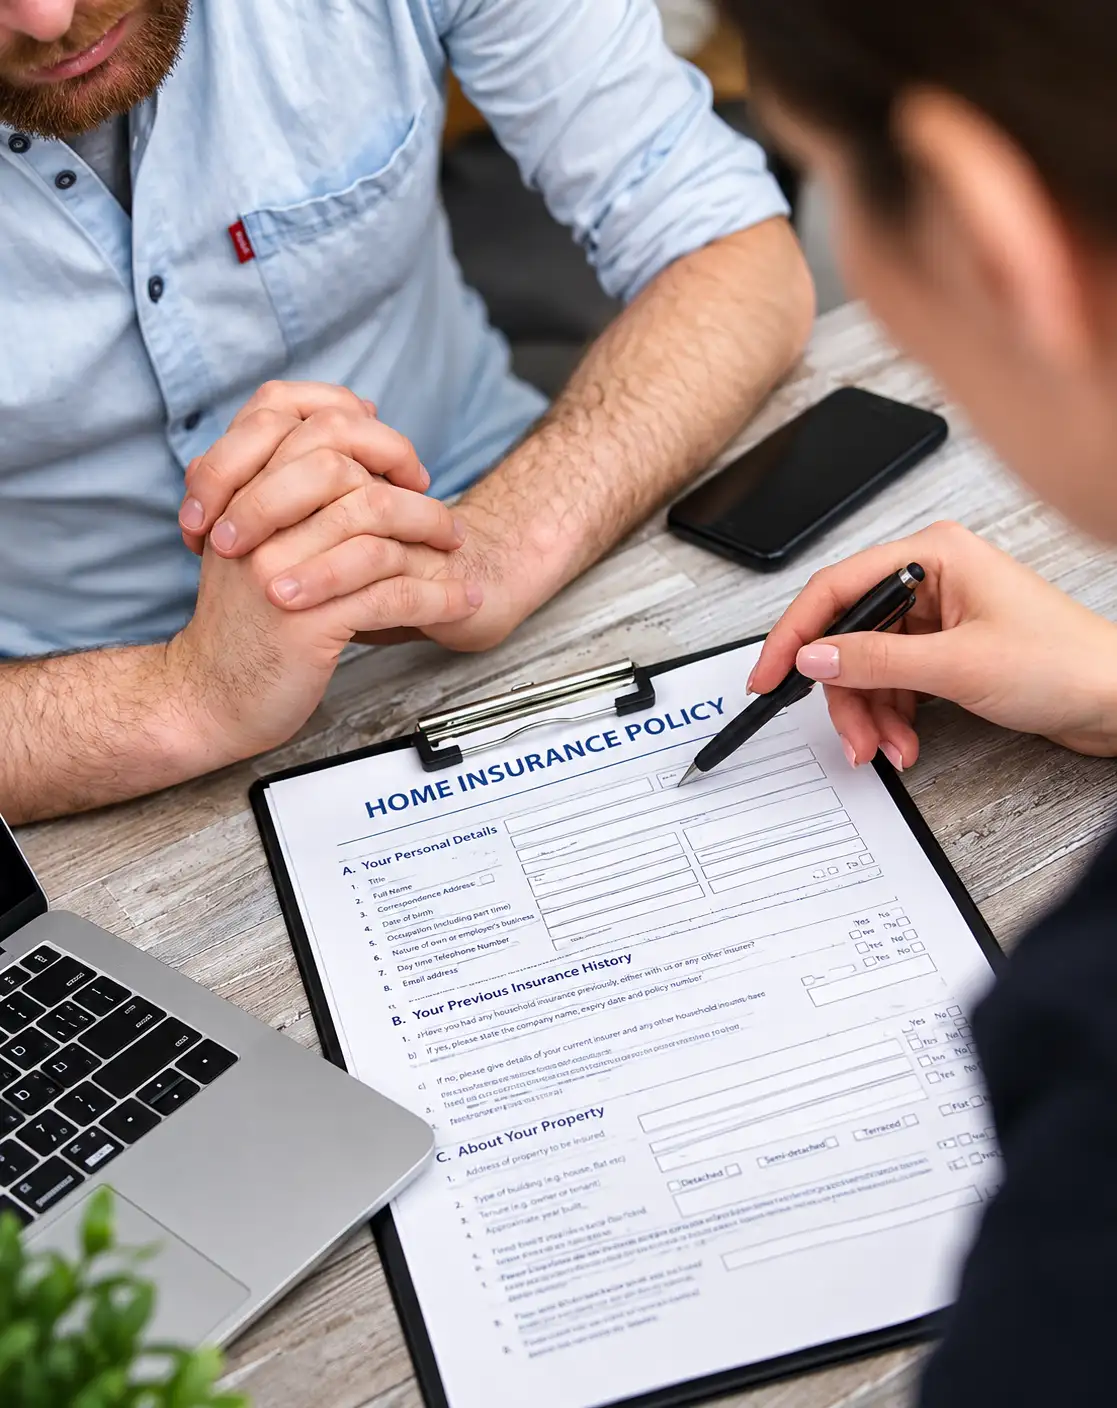
  • An adjuster reviewing a home insurance policy form with a homeowner
    Step 01 of 05

    Free Claim Review

    We review your policy and the damage at no cost, and tell you honestly whether hiring a public adjuster makes sense.

    • Policy review
    • Damage walkthrough
    • No-obligation advice
  • An inspector in a hard hat and safety vest checking a front door with a clipboard
    Step 02 of 05

    Inspection & Documentation

    We inspect every part of the property, photograph and measure the damage, and build a detailed line-by-line estimate.

    • Full property inspection
    • Photo & video evidence
    • Line-item estimate
  • Two people going over claim paperwork together at a table
    Step 03 of 05

    Claim Filing

    We prepare and submit your claim with the evidence to back it up, and handle every form, deadline, and call with your insurer.

    • Proof of loss
    • Supporting documents
    • Insurer communication
  • A handshake across a desk covered in financial charts
    Step 04 of 05

    Negotiation

    When the insurer’s adjuster undervalues the damage, we push back with documentation until the offer reflects the full loss.

    • Counter-estimates
    • Re-inspections
    • Appeals if needed
  • A hand signing a contract with a pen
    Step 05 of 05

    Settlement

    Once a fair settlement is reached, the insurer issues payment. Our fee comes out of the settlement, never out of your pocket.

    • Final agreement
    • Payment issued
    • Fee from settlement

Step 1 of 5

Why Fortify

Your Claim Deserves a Higher Standard.

A lit two-story home at dusk surrounded by landscaping
Every inch documented

Fortify Alliances proves a claim can be handled with persistence and care: we fight your insurer for every dollar while keeping you informed at every step.

  • $0 upfront: we only get paid when you do
  • Available 24/7 after a storm or loss
  • Se habla español
Book a free claim
Portrait of a Fortify Alliances public adjuster
“We treat every claim like it’s our own home on the line.”
Bryan Villa, Founder, Fortify Alliances

Trusted by homeowners, businesses & property managers
  • Logo
  • Logo
  • Logo
  • Logo
  • Logo

Real Claims, Real Results

Our Results

See all results
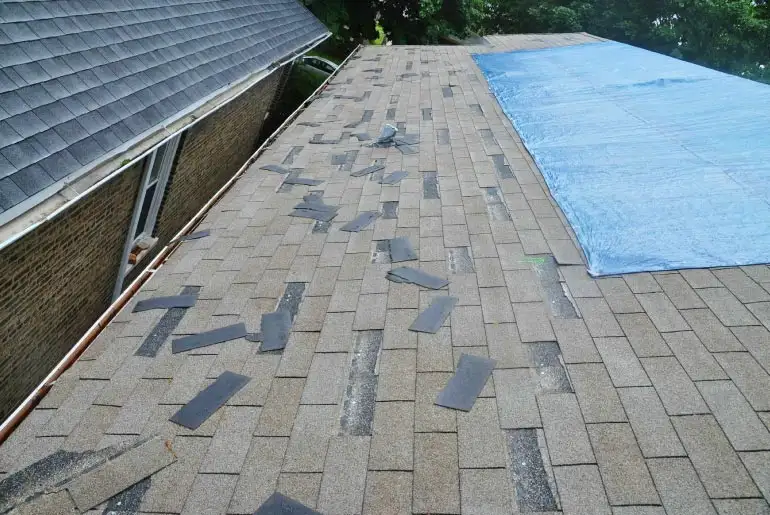
  • A hail-damaged shingle roof with loose shingles and a blue tarp
    Residential

    Naperville, IL

    Settled in 94 days

    Hail-Damaged Roof & Siding

    • Storm & Hail
    • Roof Replacement
    • +1

    The insurer’s first offer covered spot repairs only. We documented hail impacts on every roof slope, siding wall, and gutter run, then negotiated a full replacement.

    Insurer’s first offer$12,300

    Final settlement$68,900

    View case study
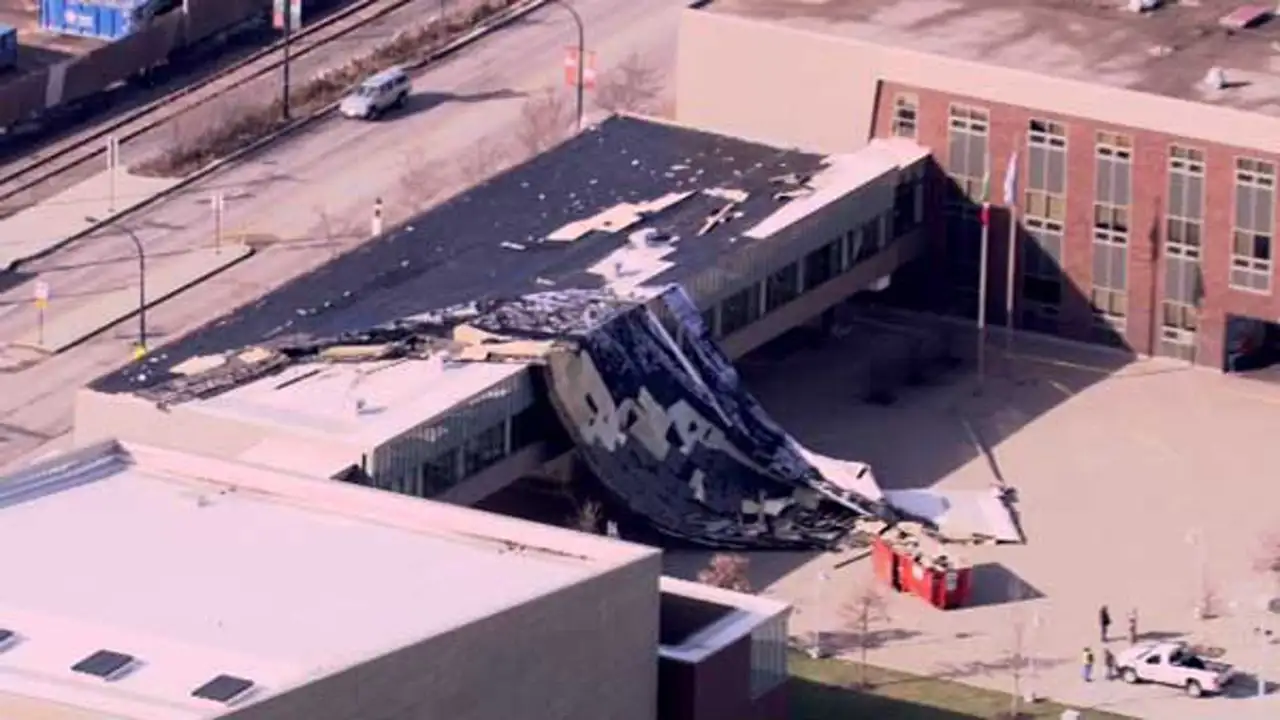
  • Aerial view of a commercial building with its roof torn open by wind
    Commercial

    Schaumburg, IL

    Settled in 121 days

    Wind & Water Damage, Retail Plaza

    • Wind
    • Water Intrusion
    • +2

    A windstorm tore roofing from a six-unit plaza and flooded three tenant spaces. We scoped damages, including business interruption, and secured a settlement.

    Insurer’s first offer$41,000

    Final settlement$96,500

    View case study

FAQ

Frequently Asked Questions

Everything you need to know about working with a public adjuster, from cost to timelines, all in one place.

Still have questions?Call (312) 687-2604
What does a public adjuster do?
A public adjuster is a licensed insurance professional who represents you, not the insurance company. We review your policy, document and value the damage, prepare your claim, and negotiate with your insurer so you receive the full settlement you’re owed.
How much does it cost to hire you?
Nothing upfront. We work on contingency: our fee comes out of your settlement, never out of your pocket, so we only get paid when you do. Your first claim review is free.
When should I call a public adjuster?
As soon as you can after a storm, fire, or water loss. We’re available 24/7, and a free claim review will tell you honestly whether hiring a public adjuster makes sense.
My claim was denied or underpaid. Can you still help?
In many cases, yes. We review your policy and the insurer’s decision, document the full extent of the damage, and push back with counter-estimates, re-inspections, and appeals if needed.
How long does the claims process take?
It depends on the size of the loss and how your insurer responds. We handle every form, deadline, and follow-up to keep things moving. The claims in Our Results settled in 94 and 121 days.
Do you handle residential and commercial claims?
Yes. We handle homes as well as retail, office, industrial, and apartment buildings, including business interruption claims.
Free Claim Review

Don’t Settle for Less Than Your Claim Is Worth.

Fortify Alliances reviews your policy and your damage at no cost, and we only get paid when you do.

Book a free claim
Free Claim Review

Tell Us About Your Claim.

Share a few details and a licensed adjuster will reach out to review your policy and damage. No upfront cost, no obligation.

Property type
Type of damage
Have you filed a claim?

By submitting, you agree to be contacted about your claim by phone or email.